CBRE's H1 report has a number most people skimmed past.
Yotta 2026 last week was in some ways a validation of what we have been focusing at ReadyInfra. The emerging importance of the metro-adjacent inference data centers.
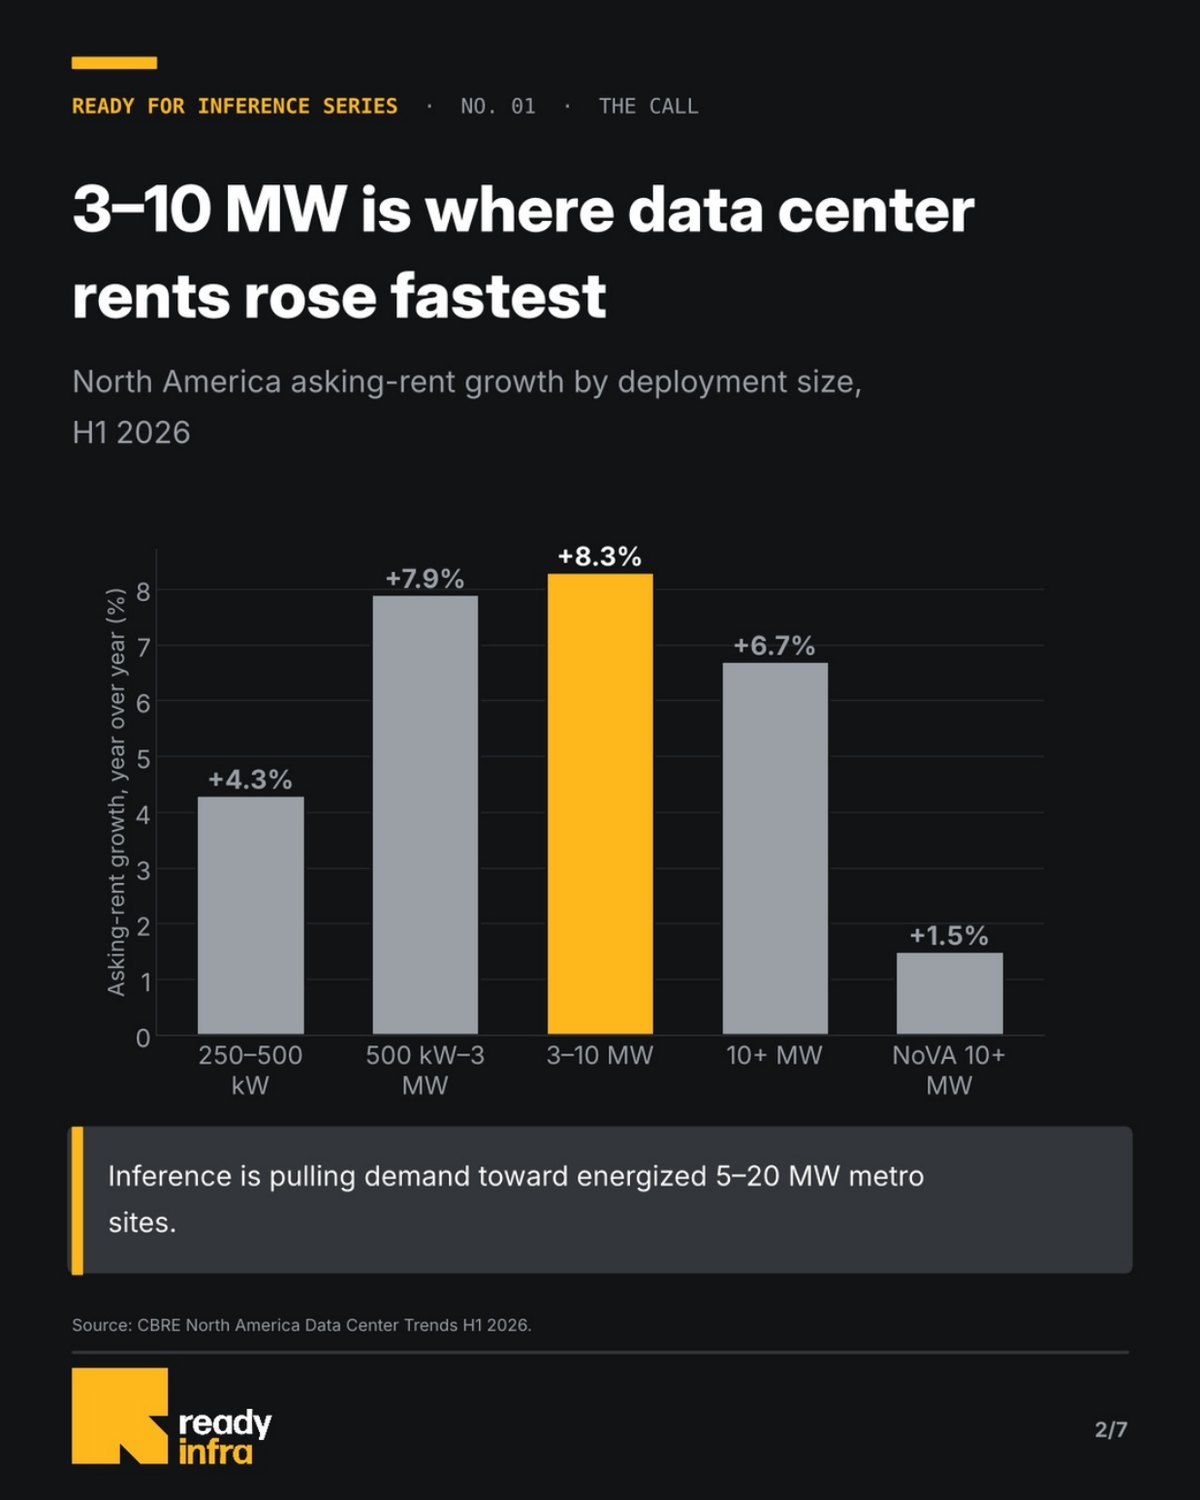
Asking rents for 3–10 MW deployments were up 8.3%. That's the fastest of any size band. The 10 MW+ band was up 6.7%.
For years the best pricing went to whoever could take the biggest block. Inference is starting to change that. Training wants the cheapest megawatt it can find, wherever it is. Inference wants a megawatt close to users, fiber and the cloud on-ramps. Once a model is earning revenue, latency and egress cost matter more than raw compute.
Look at the deals from the last ten days.
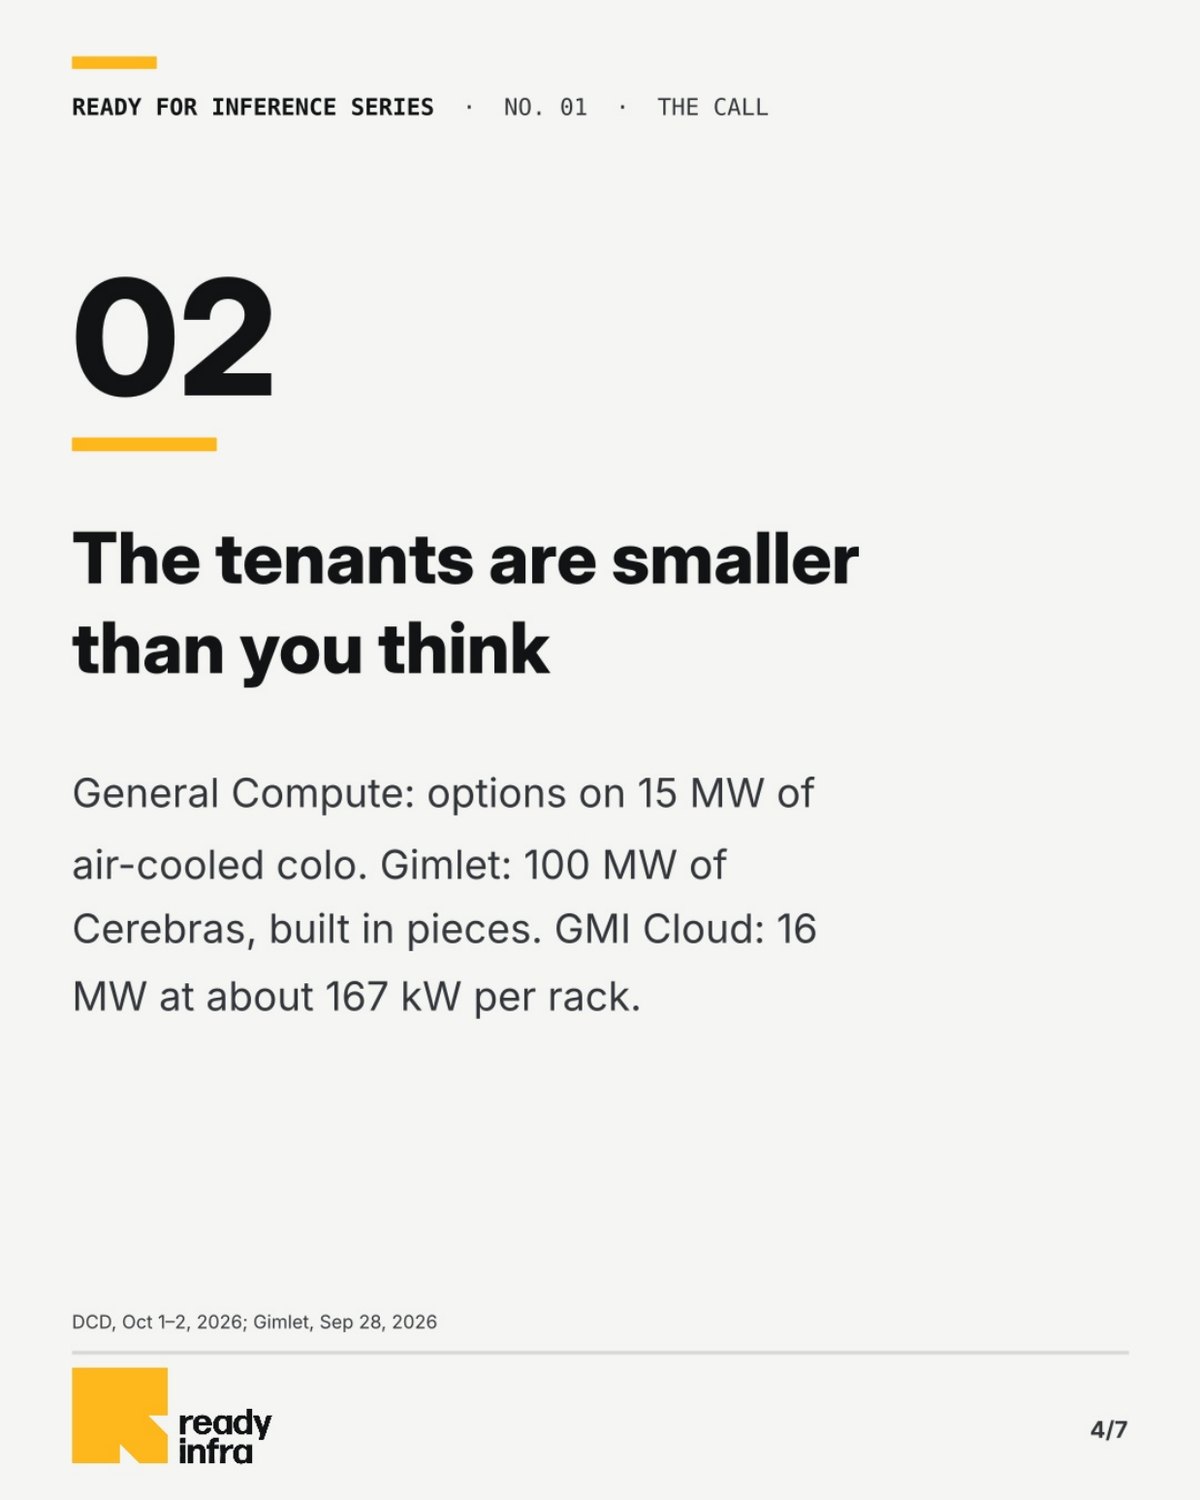
- General Compute took options on 15 MW of air-cooled colo for a mix of Nvidia, SambaNova and Cerebras gear.
- Gimlet announced 100 MW of Cerebras capacity, rolled out site by site.
- GMI Cloud put roughly 7,000 GB300s into 16 MW in Taiwan. That works out to about 167 kW a rack.
Here's where I land. The next couple of years of inference leasing will go to whoever controls energized 5–20 MW in a metro. Land and shells aren't the bottleneck. A signed utility agreement with a real date on it is.
If you've been working on 5–20 MW metro sites, what are inference tenants asking for first? Power date, density or latency?
The conversation on this one is happening on LinkedIn.
Join the discussion →